A car with its taillights on, pulled onto the grassy shoulder of a wet, palm-lined road at night

Orlando Uninsured Motorist Attorneys

Hit by a Driver With No Insurance? Talk to an Orlando Uninsured Motorist Lawyer Who Takes On Your Own Insurer.

If you were hurt in Orlando or Central Florida by a driver with no insurance, too little insurance or who fled, your own UM/UIM coverage may pay. Our uninsured motorist attorneys find every policy that applies and make your insurer honor what you paid for. No fee unless we win. Call (407) 777-8888

  • No fee unless we win
  • Se habla español
  • Talk to an attorney, not a call center
Signature result
$1.2MJury verdict after a $30K offer
Languages
EN / ESSe habla español

Free Case Review

Hit by an uninsured driver? Tell us what happened.

100% confidential. We never share your information. This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

“The reviews speak for themselves. Trust in the process — Alexandra will deliver.”
Andrew Christiansen

What's at Stake

Your Own Insurer Isn't on Your Side in a UM Claim

We're sorry this happened. You paid premiums for years, but when you file a UM claim, your insurer's job is to pay as little as possible. Here's what you're up against.

  • The friendly recorded statement

    Your own adjuster may ask to record your account. Policies require cooperation, but what you say can still be used to cut the claim.

  • Coverage you don't know you have

    Stacked limits, household vehicles and resident relatives' policies are easy to miss — and insurers won't point them out.

  • The lowball offer

    Insurers often value UM claims as if your injuries were minor. Accepting can mean leaving coverage you paid for on the table.

  • Deadlines and notice rules

    Your policy has notice requirements, and the claim against the at-fault driver generally must be filed within two years.

Let us handle the insurance company.

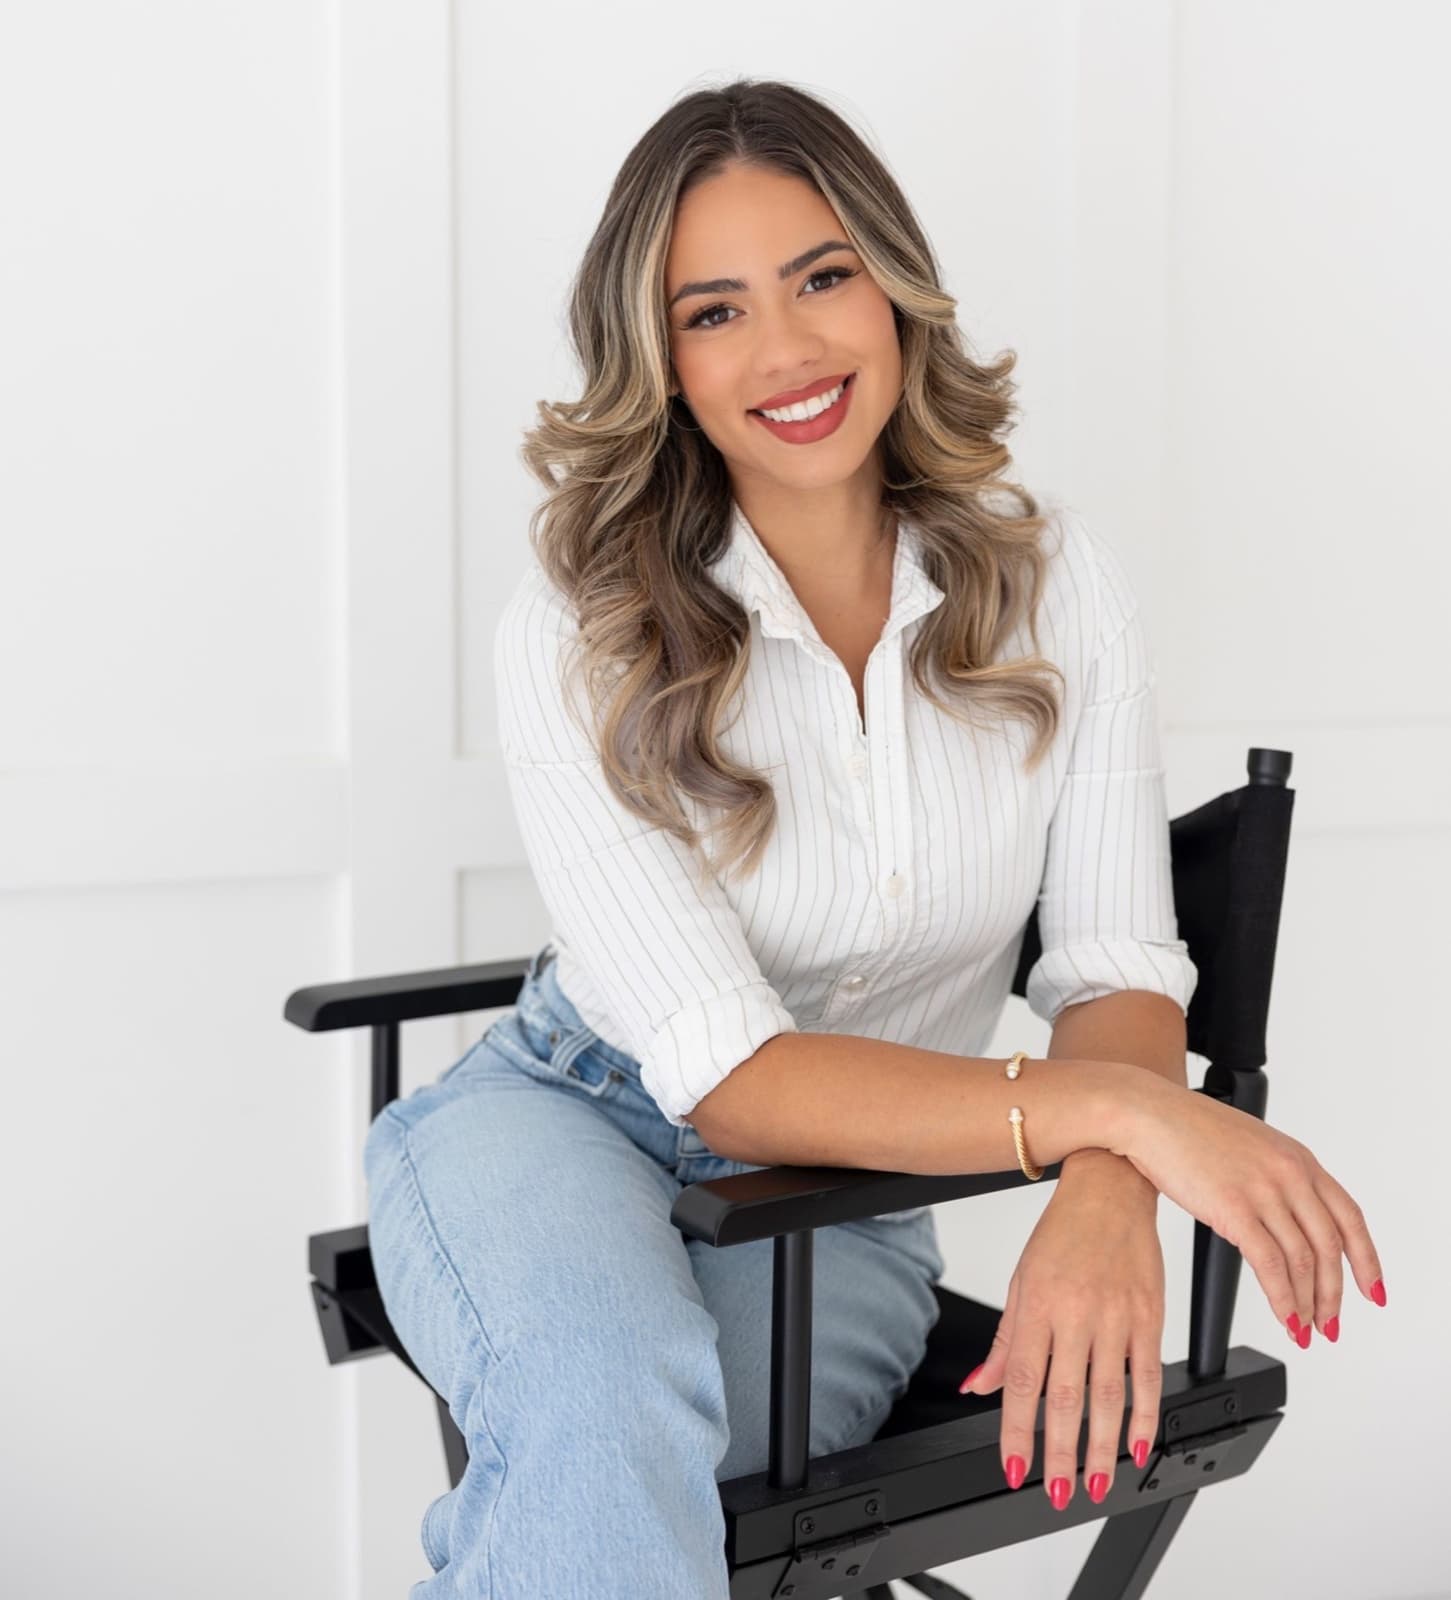
Alexandra Tosado, founding attorney of ANT Law Firm

Alexandra Tosado · Founding Attorney

Our promise
You paid for this coverage. We make sure your insurer pays what it owes.

Why You Need a Lawyer

Why You Need an Uninsured Motorist Attorney in Orlando

Florida only requires drivers to carry $10,000 in personal injury protection and $10,000 in property damage liability. Bodily injury liability coverage — the insurance that pays for injuries a driver causes to others — isn't required for most drivers, and Florida has one of the highest rates of uninsured drivers in the country. On I-4, the 408, Colonial Drive and every road in Central Florida, the driver who hits you may have nothing to pay for your injuries.

That's what uninsured and underinsured motorist (UM/UIM) coverage is for. It pays for your injuries when the at-fault driver has no bodily injury coverage, too little coverage, or can't be identified after a hit and run. In Florida, UM coverage generally follows you, not the car, so it may also apply if you were hit as a pedestrian, a cyclist or a passenger.

Here's the catch: a UM claim is against your own insurance company. It has adjusters and lawyers whose job is to dispute your injuries and minimize the payout. One of our attorneys used to defend insurance companies, so we know how they evaluate UM claims. We review every policy in your household, handle every call, and prepare your case for a jury if your insurer won't pay fairly.
  • Every household policy reviewed
  • Stacked coverage identified
  • Your insurer's calls handled for you
  • Bad-faith conduct documented
  • Your case built for a jury from day one
  • Updates in English or Spanish

Step-by-Step

What to Do After Being Hit by an Uninsured Driver

Finding out the other driver has no insurance is stressful, but you likely have more options than you think. These steps protect your UM claim.

Just been in a crash?

Talk to an attorney before you talk to the insurance company. It's free, and it could protect your claim.

  1. 01

    Call 911 and get a police report

    The report documents the crash and whether the other driver had insurance. Ask the officer for the report number.
  2. 02

    Get the other driver's information anyway

    Name, address, license number, plate and vehicle — even if they say they have no insurance. It matters for your UM claim.
  3. 03

    Don't skip this

    Get medical care within 14 days

    Your PIP pays first, and gaps in treatment give your UM insurer reasons to pay less. Florida PIP can deny benefits if you wait more than 14 days.
  4. 04

    Document everything

    Photos of the vehicles, the scene, road conditions and your injuries. Keep every bill, receipt and pay stub.
  5. 05

    Notify your insurer, but be careful

    Report the crash promptly as your policy requires, but don't give a recorded statement or accept an offer before talking to an attorney.
  6. 06

    Call an Orlando uninsured motorist attorney

    We'll review your policies for free and find every source of coverage. Call (407) 777-8888 for a free case review.

We Try Cases

Insurers Pay More — Even Your Own — When They Know You'll Go to Trial

Your insurer is deciding right now how little it can pay on your UM claim. Here's what happens when an insurer guesses wrong.

“Hired ANT Law Firm after I got involved in a car accident and I'm glad that I worked with them. They are professionals and know what they're doing.”
Michael Kuzin · March 2024

Landmark verdict

40×

The jury's verdict was forty times the insurance company's offer.

Their offer

$30,000

The jury's verdict

$1.2M

The insurance company offered our client $30,000. We turned it down, built the case for trial and put it in front of a jury. The jury awarded $1.2 million — forty times what the insurer said the case was worth.

Jury VerdictPublic Transportation NegligenceOrange County, FL

Past results do not guarantee future outcomes. Every case is different and is evaluated on its own facts. Amounts are gross recoveries before fees, costs and liens.

The Plan

Three Steps From Crash to Compensation

You don't need to read your policy or know how UM works. You just need to make the first call.
  1. 01

    Tell us what happened.

    Call, text or fill out the form. It's free and confidential.

  2. 02

    We build your case for trial.

    We investigate, gather the evidence, handle the insurance company and get your medical care documented.

  3. 03

    You get paid what you deserve.

    We negotiate from strength. If they won't pay fairly, we take it to a jury.

No fee unless we win · Se habla español

How Our Uninsured Motorist Attorneys Build Your Claim for Trial

A UM claim is won with the right policy review and solid medical evidence. Here's what happens once you hire us.

  1. We review every policy

    Your policy, household vehicles and resident relatives' policies, stacking elections and any signed UM rejection forms.
  2. We put your insurer on notice

    We report the UM claim properly, protect your rights under the policy, and take over all communication.
  3. We document your injuries

    We work with your doctors to record every injury, track every bill and get clear opinions on future care.
  4. We demand full value and negotiate

    A detailed demand to your insurer, and pressure under Florida's bad-faith law when it refuses to be reasonable.
  5. We file suit and try your case

    If your insurer won't pay fairly, we file suit and take your UM claim to a jury.

Compensation

Uninsured Motorist Compensation: What You Can Recover

UM coverage pays what you could have recovered from the at-fault driver if they'd been properly insured, up to your UM limits. PIP pays first.

  • Medical expenses

    Past and future: ER visits, surgery, therapy, imaging, medication and long-term care beyond PIP.

  • Lost wages and earning capacity

    Paychecks you missed while recovering and income you can no longer earn.

  • Pain and suffering

    Physical pain, emotional distress and the loss of things you used to enjoy.

  • Underinsured gap

    The difference between the at-fault driver's too-small policy and your actual losses, up to your UIM limits.

  • Out-of-pocket costs

    Rides to appointments, home help, childcare and other costs the crash caused.

  • Loss of consortium

    The impact of your injuries on your marriage and family life.

  • Stacked coverage

    If your policy is stacked, UM limits for each vehicle on the policy may be combined.

  • Bad-faith damages

    If your insurer acts in bad faith, Florida law may allow recovery beyond your policy limits.

Not sure what your case is worth? We'll tell you, free.

Get My Free Case Review

Florida Law

Florida UM/UIM Law and Your Rights

Florida's uninsured motorist statute, Fla. Stat. § 627.727, sets the rules for these claims. Here's what matters for your case.

Bodily injury coverage required
$0Most Florida drivers aren't required to carry insurance for injuries they cause.
PIP coverage
$10,000Your own policy pays first: 80% of medical bills and 60% of lost income.
Deadline to sue the driver
2 yearsFor most injury claims from crashes on or after March 24, 2023.
Fault limit
50%Found more than 50% at fault? You can't recover from the driver or under UM.

Insurers must offer UM. Under Fla. Stat. § 627.727, a policy with bodily injury liability coverage must include UM coverage equal to those limits unless you rejected it or chose lower limits in writing on an approved form. UM isn't required, but if nobody in your household signed a rejection, you may have more coverage than you think.

Stacked or non-stacked. Stacked coverage can let you combine UM limits for each vehicle on your policy. Many Florida policies are sold as non-stacked after the policyholder signs a selection form, which limits coverage to a single vehicle. We check which you have.

Underinsured drivers. Florida's UM coverage also pays when the at-fault driver's liability limits are too low for your losses. It can pay on top of their policy, up to your UM limits.

Bad faith. If your insurer doesn't try in good faith to settle when it could and should, Florida's bad-faith statute (Fla. Stat. § 624.155) can allow damages beyond your policy limits. It first requires a Civil Remedy Notice, which gives the insurer 60 days to fix the problem.

What Success Looks Like

What Life Looks Like When Your Case Is Handled

You're not arguing with your own insurer or wondering what your policy covers. Every policy has been found, your treatment is covered, and someone is pushing for what your claim is really worth.
Get My Free Case Review

Facing it alone

  • Overwhelmed and confused
  • Pushed around by an adjuster
  • Worried about every bill
  • Just a file number

With ANT in your corner

  • Informed and in control
  • Taken seriously by the insurance company
  • Secure enough to focus on healing
  • Treated like a person, in English or Spanish
  • 01

    Treatment covered

    Doctors, therapy and the care you'll need in the future.

  • 02

    Income replaced

    The paychecks you missed and the earning power you lost.

  • 03

    Every policy used

    Your coverage, household policies and stacking, not just the obvious one.

  • 04

    Peace of mind

    Someone handled it, and you were treated with respect.

Every case is different. Past results don't guarantee a similar outcome.

Client Reviews

What Our Car Accident Clients Say

Real Google reviews from people who were hurt in crashes and trusted us with their case.
5.0 130+ reviews on Google(opens in new tab)
  • “I had a car accident almost 2 years ago and the previous law firm wasn't able to work my case. A good friend referred me to ANT Law Firm, and our process was flawless since they took over.”
    Gio Gautier· Car accident
  • “This was the first time that I had to seek out a lawyer due to an injury from a car accident and I'm so glad I chose them to represent me. They always called with updates on my case.”
    Sarah King· Car accident
  • “A very positive experience with the attorney and her entire team — always attentive, kind, and willing to clarify every question. The fact that they are bilingual is a huge plus.”
    Olga Patricia Ramirez· January 2026

Why ANT Law Firm

Why Orlando Drivers Choose ANT Law Firm for UM Claims

After a crash with an uninsured driver, your own insurance company offers as little as it can get away with. We build every UM claim for trial, so your insurer has to take it seriously — and you pay nothing unless we win.

  • You pay nothing up front. No fee unless we win.
  • You work directly with an attorney, not a call center.
  • Se habla español — our whole team is bilingual.
  • We prepare every case as if it's going to trial.

Straight Answers

Uninsured Motorist Lawyer FAQ

Answers to the questions our Orlando uninsured motorist attorneys hear most often.

What is uninsured motorist (UM) coverage in Florida?

UM coverage is part of your own auto policy. It pays for your injuries when the at-fault driver has no bodily injury liability insurance, can't be identified after a hit and run, or — as underinsured motorist (UIM) coverage — has limits too low to cover your losses. Under Fla. Stat. § 627.727, insurers must include UM coverage equal to your bodily injury limits unless you rejected it or chose lower limits in writing.

Is uninsured motorist coverage required in Florida?

No. UM coverage isn't mandatory, but insurers must offer it with any policy that includes bodily injury liability coverage. You can only reject it or choose lower limits by signing an approved written form. If no one signed that form, you may have UM coverage equal to your bodily injury limits. Our attorneys will review your policy for free.

Will my insurance rates go up if I file a UM claim?

Florida law generally prohibits insurers from adding a surcharge or raising your premium because of an accident unless they determine in good faith that you were substantially at fault. If an uninsured driver caused the crash, that usually isn't the case. If your insurer treats you unfairly after a not-at-fault claim, our attorneys can push back.

Can I file a UM claim after a hit and run accident?

Yes. Hit and runs are one of the most common reasons for UM claims. When the at-fault driver flees and is never identified, UM coverage generally treats them as uninsured. Report the crash to police right away and preserve every piece of evidence. Without an independent witness or footage, insurers often dispute whether another vehicle was involved.

What is stacking vs. non-stacking UM coverage?

Stacked coverage can let you combine the UM limits for each vehicle on your policy. For example, $100,000 in UM coverage on three vehicles could provide up to $300,000 if your policy is stacked. Non-stacked coverage limits you to one vehicle's coverage. Stacking costs more, and many Florida policies are sold as non-stacked after the policyholder signs a selection form. We'll check which you have.

How much uninsured motorist coverage should I carry in Florida?

Because Florida doesn't require most drivers to carry bodily injury coverage, many people choose UM limits at least equal to their own bodily injury limits. Medical bills after a serious crash can easily exceed $100,000. Higher limits and stacked coverage cost more but provide more protection. Talk to your insurance agent about what fits your household.

What if my own insurance company denies my UM claim?

Your insurer has a financial reason to deny or minimize your claim. If it denies, delays or undervalues a claim without a good reason, it may be acting in bad faith under Fla. Stat. § 624.155. A bad-faith claim requires a Civil Remedy Notice and gives the insurer 60 days to cure, but it can lead to damages beyond your policy limits. We also file suit on the UM claim itself and take it to a jury when needed.

What's the difference between uninsured motorist (UM) and underinsured motorist (UIM) coverage?

Uninsured motorist coverage applies when the at-fault driver has no bodily injury liability insurance or can't be identified. Underinsured motorist coverage applies when the driver has insurance, but not enough to cover your losses. For example, if your damages are $200,000 and the driver's policy is $10,000, UIM can help cover the gap, up to your limits. In Florida, both are part of the same UM coverage.

Still have a question? Call (407) 777-8888 or send us a message.

Orlando Uninsured Motorist Attorneys

Don't Face the Insurance Company Alone

You paid for this coverage. You focus on healing — we'll find every policy and handle your insurer. Your free case review takes a few minutes, in English or Spanish.

  1. 1Tell us what happened.
  2. 2We build your case for trial.
  3. 3You get paid what you deserve.
  • No fee unless we win
  • Se habla español
  • Free & confidential
Call Us